904-257-3673
 contact@liebermanfirm.com
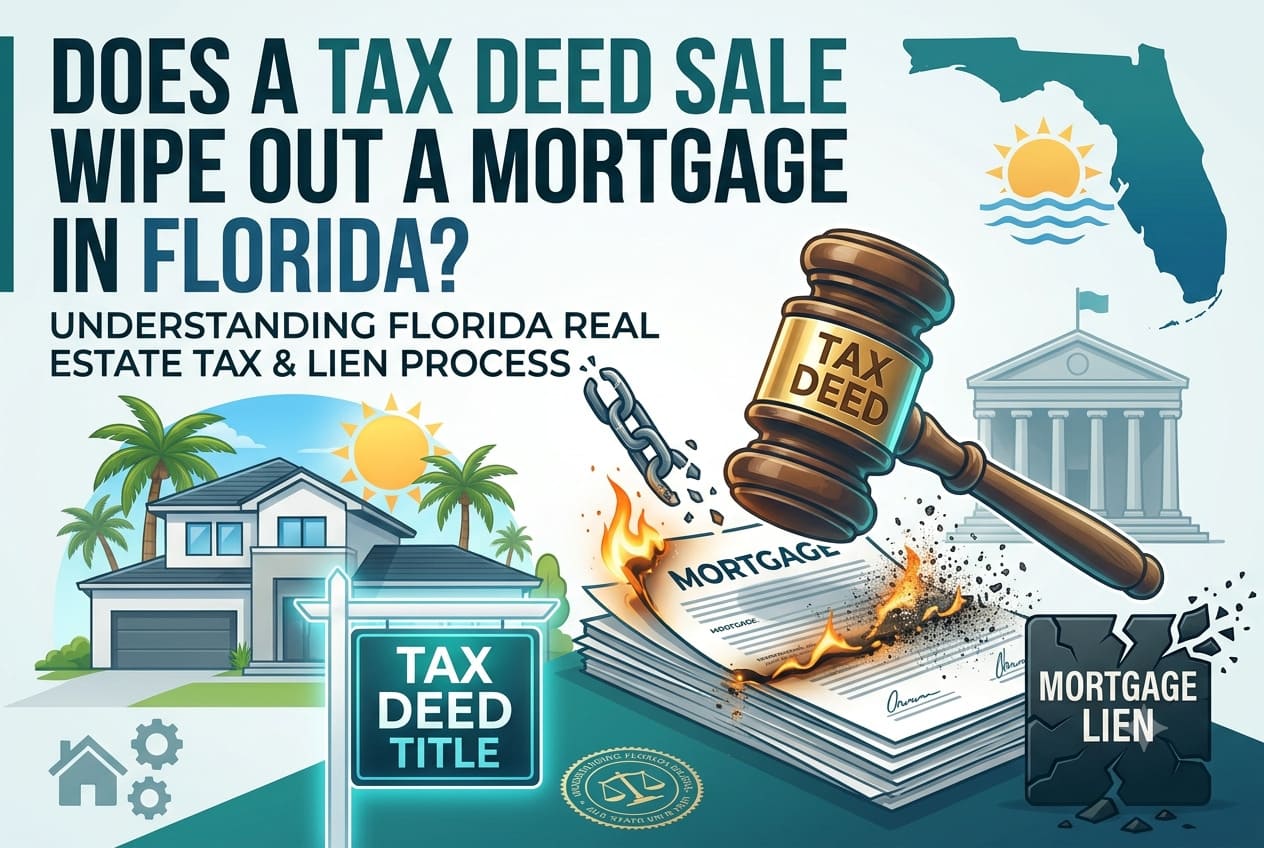
Quick answer: In Florida, a tax deed sale generally extinguishes most junior liens, including mortgages, once the deed is issued and the redemption period has passed. However, certain liens—such as those held by the federal government—may survive the sale. Both buyers and lenders should consult a real estate attorney before acting.
Property taxes in Florida are not optional. When a homeowner stops paying them, the state has a legal mechanism to recover that debt—and it can move faster than most people expect. For homeowners carrying a mortgage, this raises an urgent question: if the property goes to a tax deed sale, what happens to the lender’s interest?
The answer matters enormously. A lender could lose its security interest entirely. A buyer could acquire property encumbered by debts they didn’t anticipate. Understanding how Florida’s tax deed process works—and how it interacts with mortgages—is essential for anyone involved in Florida real estate.
Florida’s tax deed process begins when a property owner fails to pay real estate taxes. Under Florida Statutes Chapter 197, when taxes go unpaid, the county sells a tax certificate to investors at a public auction. That certificate earns interest and gives the investor the right to collect the debt.
If the property owner still doesn’t pay after a minimum of two years, the tax certificate holder can apply for a tax deed. The county clerk then schedules a public auction. The winning bidder at that auction receives a tax deed—a legal instrument that transfers title to the property.
Here’s the critical point: a tax deed issued through Florida’s statutory process is not just a conveyance of title. It is a mechanism that can eliminate competing claims on the property, including mortgages.
When a Florida homeowner takes out a mortgage, they retain legal title to the property. The lender holds a lien—a security interest recorded against the title. This means the lender has a legal claim to the property if the borrower defaults, but the borrower is still the owner of record.
This distinction matters in a tax deed scenario. The homeowner—not the lender—is responsible for paying property taxes. If the homeowner fails to pay, the tax certificate and eventual tax deed process moves forward regardless of what the lender does. A lender cannot simply step in and stop the process unless it takes affirmative action, such as paying the delinquent taxes itself.
Generally, yes—a tax deed sale in Florida can wipe out a mortgage. Under Florida law, when a tax deed is issued following a completed sale, it conveys title free and clear of most liens that are subordinate to the tax lien. Since property tax liens take priority over virtually all other claims under Florida Statutes § 197.122, a properly conducted tax deed sale will typically extinguish a first mortgage.
This outcome has been consistently upheld by Florida courts. The reasoning is straightforward: property taxes represent a government interest that supersedes private contractual arrangements. A lender’s mortgage, no matter how large or how recently recorded, ranks below the state’s claim for unpaid taxes.
Not every lien disappears after a tax deed sale. Florida law carves out several important exceptions:
For this reason, title searches and legal review are essential before purchasing a property at a tax deed sale or immediately after.
When a mortgage is extinguished by a tax deed sale, the lender loses its security interest in the property. The lender’s only remaining recourse is against the borrower personally—assuming the loan was a recourse loan and the lender is willing to pursue collection.
This is precisely why sophisticated institutions utilize dedicated commercial lending and loss mitigation counsel to monitor property tax payments closely. Many mortgage servicers maintain escrow accounts specifically to pay property taxes on behalf of the borrower, preventing this scenario from occurring in the first place.
While a tax deed sale generally extinguishes a lender’s mortgage lien, it does not necessarily mean the lender walks away completely empty-handed. In many cases, tax deed properties sell at auction for significantly more than the back taxes and administrative fees owed to the county.
The money left over after satisfying the tax debt is known as surplus funds. Under Florida law, these funds do not belong to the county or the new buyer. Instead, the county clerk holds them, and subordinate lienholders—including the mortgage lender whose lien was just wiped out—have a statutory right to file a claim for these funds.
For lenders, monitoring the tax deed sale and aggressively pursuing surplus funds is often the best way to mitigate financial losses after a security interest is compromised.
Yes—but only if the lender acts before the sale is completed. Florida Statutes § 197.502 requires the county to notify all parties with a recorded interest in the property before a tax deed auction is held. This notice gives a lender the opportunity to pay the outstanding taxes and redeem the certificate, which stops the auction from proceeding.
If a lender receives notice and fails to act, it forfeits that protection. Once the tax deed is issued and the title vests in the new buyer, the lender’s lien is gone.
Buying property at a tax deed sale can seem like an attractive investment. Prices are often well below market value. But buyers face real legal risks if they skip due diligence.
A few critical steps before bidding:
Purchasing tax deed properties without legal guidance has led to costly disputes. A clean-looking title can carry hidden issues that only become apparent after the purchase.
Many investors assume that because a tax deed sale wipes out mortgages and other junior liens, they automatically receive a “clean” title they can sell tomorrow. This is a dangerous misconception.
While the tax deed legally transfers ownership, major title insurance companies in Florida view tax deed properties as high-risk. Because the previous owner and lender lost their property rights through an administrative auction, title companies worry that those parties might later sue, claiming they never received proper legal notice.
Consequently, most title companies will refuse to issue title insurance on a tax deed property for a period of four years after the sale unless the buyer takes affirmative legal action. Without title insurance, you cannot sell the property to a buyer using a traditional mortgage or secure a clean refinance.
To clear this hurdle, a tax deed buyer typically must file a Quiet Title Action. This is a specific type of lawsuit brought in a Florida circuit court to formally declare that all prior claims—including any wiped-out mortgages—are permanently extinguished. Once a judge signs the final judgment, title companies will readily issue insurance. If you have recently purchased an auction property, launching an experienced Quiet Title Action service is the fastest way to establish a truly marketable, rentable, or sellable asset.
Florida’s tax deed laws are specific, and the stakes are high for both property owners and lenders. A mortgage can be extinguished, an investment can be compromised, and rights can be lost—sometimes before anyone realizes what’s happening.
Lieberman Chamberlain PLLC is a Jacksonville-based real estate law firm with deep experience in Florida property law, title matters, and commercial lending. Whether you’re a lender concerned about a borrower’s delinquent taxes, an investor evaluating a tax deed purchase, or a homeowner trying to protect your property, their attorneys can provide the clear, practical guidance you need.
To speak with a mortgage attorney in Jacksonville, FL, contact Lieberman Chamberlain PLLC for a consultation at liebermanfirm.com.
Yes, in most cases. Florida law gives property tax liens priority over all other liens, including first mortgages. When a tax deed is issued following a completed sale, it generally extinguishes the mortgage lien. The lender loses its security interest in the property, though it may still pursue the borrower personally for the debt.
The process begins when a tax certificate is purchased after taxes go unpaid. The certificate holder must wait a minimum of two years before applying for a tax deed. After the application, the county schedules an auction. The entire process from initial delinquency to a tax deed auction can take two to four years or more.
Yes. A property owner can stop the sale by paying all outstanding taxes, interest, and fees before the auction takes place. This is called redemption. Florida law gives the property owner the right to redeem the property at any point before the tax deed is issued at the auction.
Federal tax liens are treated differently from state and local liens. After a tax deed sale in Florida, the IRS has 120 days to redeem the property by paying the purchase price plus interest. If the IRS does not redeem within that window, the federal lien is extinguished. Buyers of tax deed properties should account for this waiting period before assuming clear title.
Yes. Tax deed sales can offer value, but they also carry title risks that are difficult to assess without legal expertise. An experienced Florida real estate attorney can review the title, identify surviving liens, and advise on the legal steps needed to secure clear ownership after the sale.
Technically yes, but practically no. While you own the property, the title is considered unmarketable by title insurance companies for four years due to the risk of notice defects. To sell the property to a traditional buyer or get a mortgage against it, you will generally need to hire a real estate attorney to file a Quiet Title Action to clear the title.
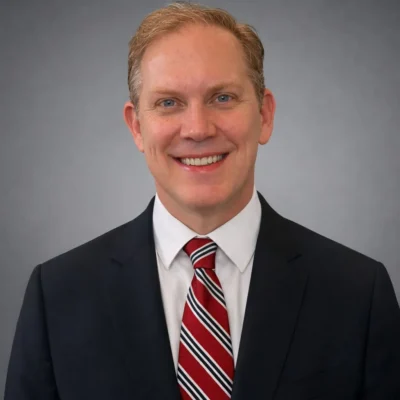
Andy Lieberman is a Florida Bar Board Certified Real Estate Attorney at Lieberman Chamberlain PLLC in Jacksonville, where he handles quiet title actions, deed disputes, and title defects for families, investors, and lenders. His more than twenty years of practice include serving as counsel to a national title insurance underwriter and owning Florida title agencies, experience that shapes how he reads a chain of title. He began his career as an Assistant Public Defender, trying cases before juries.

Based on 253 reviews
Andy and Harbor View Title have earned our trust through numerous real estate closings, from PSA review to title search examinations, insurance, and closings. At every stage, Andy and his team provided excellent, timely and cost-effective counsel. Their attention to detail and timely responses made each transaction smooth and efficient. I can strongly recommend Andy to anyone in need of real estate legal assistance.
Andy has been great to work with. He provides timely updates and explains things clearly. He is very knowledgeable and levelheaded, which is exactly what we need most times. I highly recommend him if you need legal assistance in Northeast Florida.
Worked with Lieberman Chamberlain on real estate transaction involving substantive redlines.
Andrew was responsive, thorough, and precise in his analysis, with clear communication throughout the process. Issues were identified early, addressed timely, and efficiently, with no details overlooked.
I would confidently recommend their services.
Lieberman Chamberlain is top-notch when it comes to real estate. Their team is incredibly knowledgeable and true experts in the field. I highly recommend them to anyone looking for a trusted advisor in the industry.
Don’t face your legal challenges alone. Whether you need a real estate lawyer, a personal injury attorney, or a commercial lending expert, the team at Lieberman Chamberlain PLLC is ready to help.
Call us at 904-257-3673 or fill out our online form to schedule a confidential consultation.