904-257-3673
 contact@liebermanfirm.com
By Andy Lieberman, Florida Bar Board Certified Real Estate Attorney | Lieberman Chamberlain PLLC, Jacksonville | Updated September 2026
In Brief
A Florida commercial loan is underwritten on the property or business cash flow, documented with a promissory note, loan agreement, mortgage or security agreement, and usually a personal guaranty, then closed after title, survey, lien, and entity due diligence.
Florida adds its own layer: documentary stamp tax ($0.35 per $100) and nonrecurring intangible tax (2 mills) on mortgage-secured debt, usury ceilings of 18% or 25% depending on loan size, a writing requirement for credit agreements, disclosure rules for smaller non-bank loans, and judicial foreclosure if the loan goes bad.
Most expensive problems in these deals are found in title and lien searches, not in the interest rate.
A commercial loan in Florida looks a lot like one in Ohio or Oregon until you get to the closing statement. Then the state-specific line items show up: stamp taxes that can run five figures on a mid-size mortgage, a title commitment with requirements nobody budgeted time for, and loan documents drafted around Florida rules on usury, guaranties, and foreclosure.
This guide walks through how the process actually runs, from picking a lender to what happens if the loan defaults. It is written for business owners, investors, and developers borrowing money, and for the private and regional lenders on the other side of the table. The numbers and statutes are current as of September 2026.
Commercial lending simply means credit extended to a business or for a business purpose rather than for personal or household use. Who you borrow from matters as much as how much you borrow, because each lender type prices risk differently and writes different documents.
Across all of them, underwriting keeps coming back to three numbers:
The purpose of the money drives the structure, the collateral, and the documents. Here is how the common Florida products line up.
Larger transactions may also involve letters of credit, which back a borrower’s payment or performance obligations to a third party, and interest-rate swaps, which let a borrower on a floating rate lock in a fixed cost. Swaps come with their own ISDA documents and termination costs, which borrowers routinely underestimate when they refinance early.
Timing varies with complexity. A small equipment loan or line of credit can close in one to three weeks. A commercial real estate loan more often takes 45 to 90 days, and the long pole is almost always third-party reports and title curative work, not the lender’s credit committee.
Under section 201.08, Florida Statutes, notes and other written obligations to pay money carry documentary stamp tax of $0.35 per $100 (or portion of $100). When the debt is secured by a recorded Florida mortgage, the tax is paid on the mortgage at recording and is based on the full amount secured, with no cap. Separately, section 199.133 imposes a one-time nonrecurring intangible tax of 2 mills ($2 per $1,000) on obligations secured by a mortgage or lien on Florida real property.
Two details trip people up. First, the Florida Department of Revenue caps stamp tax on an unsecured note at $2,450, a cap that disappears once the debt is secured by a recorded Florida mortgage. Second, certain renewal notes that add no new money are exempt under section 201.09, which is worth structuring around when you refinance or extend a loan with the same lender.
Here is how the taxes compare on a $1,000,000 loan:
On the mortgage-secured loan, the combined taxes total $5,500, or $5.50 per $1,000 borrowed. Revolving and future-advance facilities follow separate Department of Revenue rules on when tax is due, so the calculation is not always a straight multiplication.
Florida’s usury limits are not limited to consumer loans. Under section 687.02 and section 687.03, the ceiling is 18% simple interest per year on loans of $500,000 or less. On loans above $500,000, a rate is not usurious unless it exceeds the criminal threshold in section 687.071, which makes willfully charging more than 25% a misdemeanor and more than 45% a felony, and can render the debt unenforceable.
The trap for private and hard money lenders is that points, certain fees, and other charges for the use of money can be counted as interest and spread over the loan term when testing the rate. A 13% note with heavy points on a short-term bridge loan can test well above its face rate. Lenders should run the effective-rate math before closing, and borrowers should ask for it.
Florida’s credit agreement statute of frauds, section 687.0304, bars a borrower from suing on a credit agreement unless it is in writing, states the terms, and is signed by the lender and borrower. In practice, a loan officer’s verbal promise to extend a maturity date or waive a default is not something a borrower can enforce. Get every modification, forbearance, and extension in a signed document.
Since January 1, 2024, the Florida Commercial Financing Disclosure Law (sections 559.961–559.9615) has required non-bank providers to give written cost disclosures, including the total amount financed, total repayment, and total dollar cost, on many commercial financing transactions of $500,000 or less. The law exempts banks and other depository institutions, loans secured by real property, leases, and providers who close five or fewer Florida transactions in a calendar year. It also restricts advance fees charged by commercial financing brokers.
Florida’s version of UCC Article 9 is Chapter 679, Florida Statutes. A lender generally perfects its interest in equipment, inventory, and receivables by filing a UCC-1 with the Florida Secured Transaction Registry, and in fixtures by a fixture filing in the county where the real estate sits. Priority usually goes to whoever files first, which is why pre-closing searches matter so much.
A recent refinance handled by Lieberman Chamberlain PLLC shows why the search results matter more than the rate sheet. A family-owned distribution company on Jacksonville’s Westside was refinancing its warehouse with a regional bank to pull out equity for new racking and loading equipment. The term sheet was signed, the appraisal came in strong, and everyone expected a routine 60-day close.
The title and lien searches told a different story. An equipment lessor from years earlier still had a fixture filing of record against the property, covering conveyor systems the company believed it had paid off. There was also an unreleased notice of commencement from a roof replacement, which left open the possibility of construction lien claims. Either item would have made the bank’s mortgage less than first priority on part of the collateral, and the bank’s commitment letter required a clean first lien.
Andy Lieberman, drawing on his years as counsel to a title insurance underwriter, worked the problem from the title side. The firm tracked down the old lessor’s successor, obtained a payoff confirmation and a recorded termination of the fixture filing, and secured a contractor’s final affidavit and lien releases for the roof work so the title agent could delete the construction lien exception. The loan closed about two weeks later than planned, but the bank received the lien position it bargained for and the borrower avoided a reduced loan amount.
Client details have been changed to protect confidentiality. Every transaction turns on its own facts, and prior results do not guarantee a similar outcome.
For most closely held borrowers, the personal guaranty is the most consequential document in the stack. Three Florida-specific points deserve attention before signing:
Florida is a judicial foreclosure state. Under Chapter 702, a lender must file suit to foreclose a mortgage, and contested commercial foreclosures can take many months. Lenders sometimes use the expedited order-to-show-cause procedure in section 702.10 and often ask the court to appoint a receiver to collect rents while the case is pending.
Personal property collateral works differently. After default, a secured party may repossess equipment and other collateral without going to court as long as it does so without a breach of the peace (section 679.609), and must then dispose of it in a commercially reasonable manner.
Deadlines matter on both sides. Actions on a written contract and actions to foreclose a mortgage generally carry a five-year limitations period under section 95.11, and the one-year deficiency deadline in that statute applies only to certain owner-occupied residential property, not commercial loans. Borrowers facing default should talk to counsel before signing any forbearance agreement, because those agreements typically include releases and waivers that are hard to undo.
Beyond the statutes, Florida deals carry market-specific risk. Property and windstorm insurance costs have become a real underwriting issue, and lenders now test DSCR with current premiums rather than last year’s. For buildings in a special flood hazard area, federally regulated lenders must require flood insurance under the National Flood Insurance Act, and much of coastal Florida sits in those zones.
Florida also has niche lending markets that barely exist elsewhere, such as financing secured by timeshare receivables and resort development loans. In Northeast Florida specifically, the growth of distribution and logistics space has changed how lenders underwrite industrial property, a trend covered in our look at evolving lending strategies in Jacksonville’s industrial boom. And because so much capital comes from out of state, many Florida loans are documented by lenders unfamiliar with Florida stamp tax, usury, and homestead rules, which is where expensive mistakes tend to happen.
Borrowers tend to focus on rate and leverage. The provisions that cause trouble later are usually elsewhere: prepayment and yield-maintenance terms, cross-default clauses tied to other loans, financial covenants tested quarterly, recourse carve-outs, and cash-management triggers. On the lender side, the risk is in collateral descriptions, perfection, title exceptions, and usury exposure on private deals.
A Florida commercial lending attorney who also understands title insurance can catch many of these issues before the commitment fee is paid, when there is still leverage to fix them. For lenders, the same review is what makes the documents enforceable if the loan ever has to be collected.
Most commercial loans are priced as a spread over an index. The prime rate rose to 7.00% on September 17, 2026, after the Federal Reserve raised its target range (see the Federal Reserve H.15 release for current benchmarks), so floating-rate bank loans are generally prime plus a margin. For SBA 7(a) loans over $350,000, the SBA caps the rate at the base rate plus 3%. Fixed-rate commercial mortgages track Treasury yields plus a spread, and hard money loans typically price well above bank debt. Rates move quickly, so treat any quoted figure as a snapshot.
It is $0.35 per $100 of the amount secured, plus nonrecurring intangible tax of $2 per $1,000. On a $1,000,000 mortgage, that is $3,500 plus $2,000, or $5,500 total. Unsecured notes are capped at $2,450 in stamp tax and owe no intangible tax.
For loans of $500,000 or less, 18% per year simple interest. For loans over $500,000, the practical ceiling is 25%, the point at which criminal usury begins under section 687.071. Fees and points can count toward the effective rate.
Conventional loans usually require 20% to 35% equity. SBA 504 loans on owner-occupied property can go as low as 10% down, with higher contributions for startups and special-purpose properties such as hotels.
Often, yes, but at a price. Hard money and bridge lenders focus on collateral value, and some lenders underwrite primarily on the property’s cash flow. Expect higher rates, points, lower leverage, and shorter terms, and have the effective rate checked against Florida’s usury limits.
The lender enforces the remedies in the loan documents: judicial foreclosure of real estate under Chapter 702, repossession and sale of personal property collateral under Chapter 679, and a lawsuit against guarantors for any shortfall. Many defaults are resolved through a negotiated forbearance or loan modification before litigation.
No statute requires one, but lenders almost always have counsel drafting the documents, and those documents are written to protect the lender. Borrowers who negotiate guaranty scope, prepayment terms, and default provisions before signing usually get meaningfully better terms than those who sign the first draft.
Andy Lieberman is a Florida Bar Board Certified Real Estate Attorney with Lieberman Chamberlain PLLC in Jacksonville. With more than twenty years in practice, he advises lenders, borrowers, investors, and developers on commercial financing, title, and real estate transactions across Florida. Before establishing his own practice, he served as counsel to a national title insurance underwriter and owned Florida title agencies. He earned his J.D. from the University of San Francisco School of Law.
This article is for general informational purposes only and is not legal, tax, or financial advice. Reading it does not create an attorney-client relationship with Lieberman Chamberlain PLLC or any of its attorneys. Laws, tax rates, and interest-rate benchmarks change, and every financing transaction depends on its specific facts. Consult a licensed Florida attorney and a qualified tax professional before making decisions about a commercial loan.
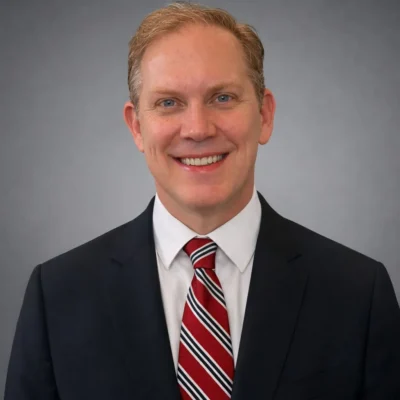
Andy Lieberman is a Florida Bar Board Certified Real Estate Attorney at Lieberman Chamberlain PLLC in Jacksonville, where he handles quiet title actions, deed disputes, and title defects for families, investors, and lenders. His more than twenty years of practice include serving as counsel to a national title insurance underwriter and owning Florida title agencies, experience that shapes how he reads a chain of title. He began his career as an Assistant Public Defender, trying cases before juries.

Based on Google Reviews
Andy and Harbor View Title have earned our trust through numerous real estate closings, from PSA review to title search examinations, insurance, and closings. At every stage, Andy and his team provided excellent, timely and cost-effective counsel. Their attention to detail and timely responses made each transaction smooth and efficient. I can strongly recommend Andy to anyone in need of real estate legal assistance.
Andy has been great to work with. He provides timely updates and explains things clearly. He is very knowledgeable and levelheaded, which is exactly what we need most times. I highly recommend him if you need legal assistance in Northeast Florida.
Worked with Lieberman Chamberlain on real estate transaction involving substantive redlines.
Andrew was responsive, thorough, and precise in his analysis, with clear communication throughout the process. Issues were identified early, addressed timely, and efficiently, with no details overlooked.
I would confidently recommend their services.
Lieberman Chamberlain is top-notch when it comes to real estate. Their team is incredibly knowledgeable and true experts in the field. I highly recommend them to anyone looking for a trusted advisor in the industry.
Don’t face your legal challenges alone. Whether you need a real estate lawyer, a personal injury attorney, or a commercial lending expert, the team at Lieberman Chamberlain PLLC is ready to help.
Call us at 904-257-3673 or fill out our online form to schedule a confidential consultation.